Wedding Loans in New Zealand: How to Finance Your Big Day Without the Stress
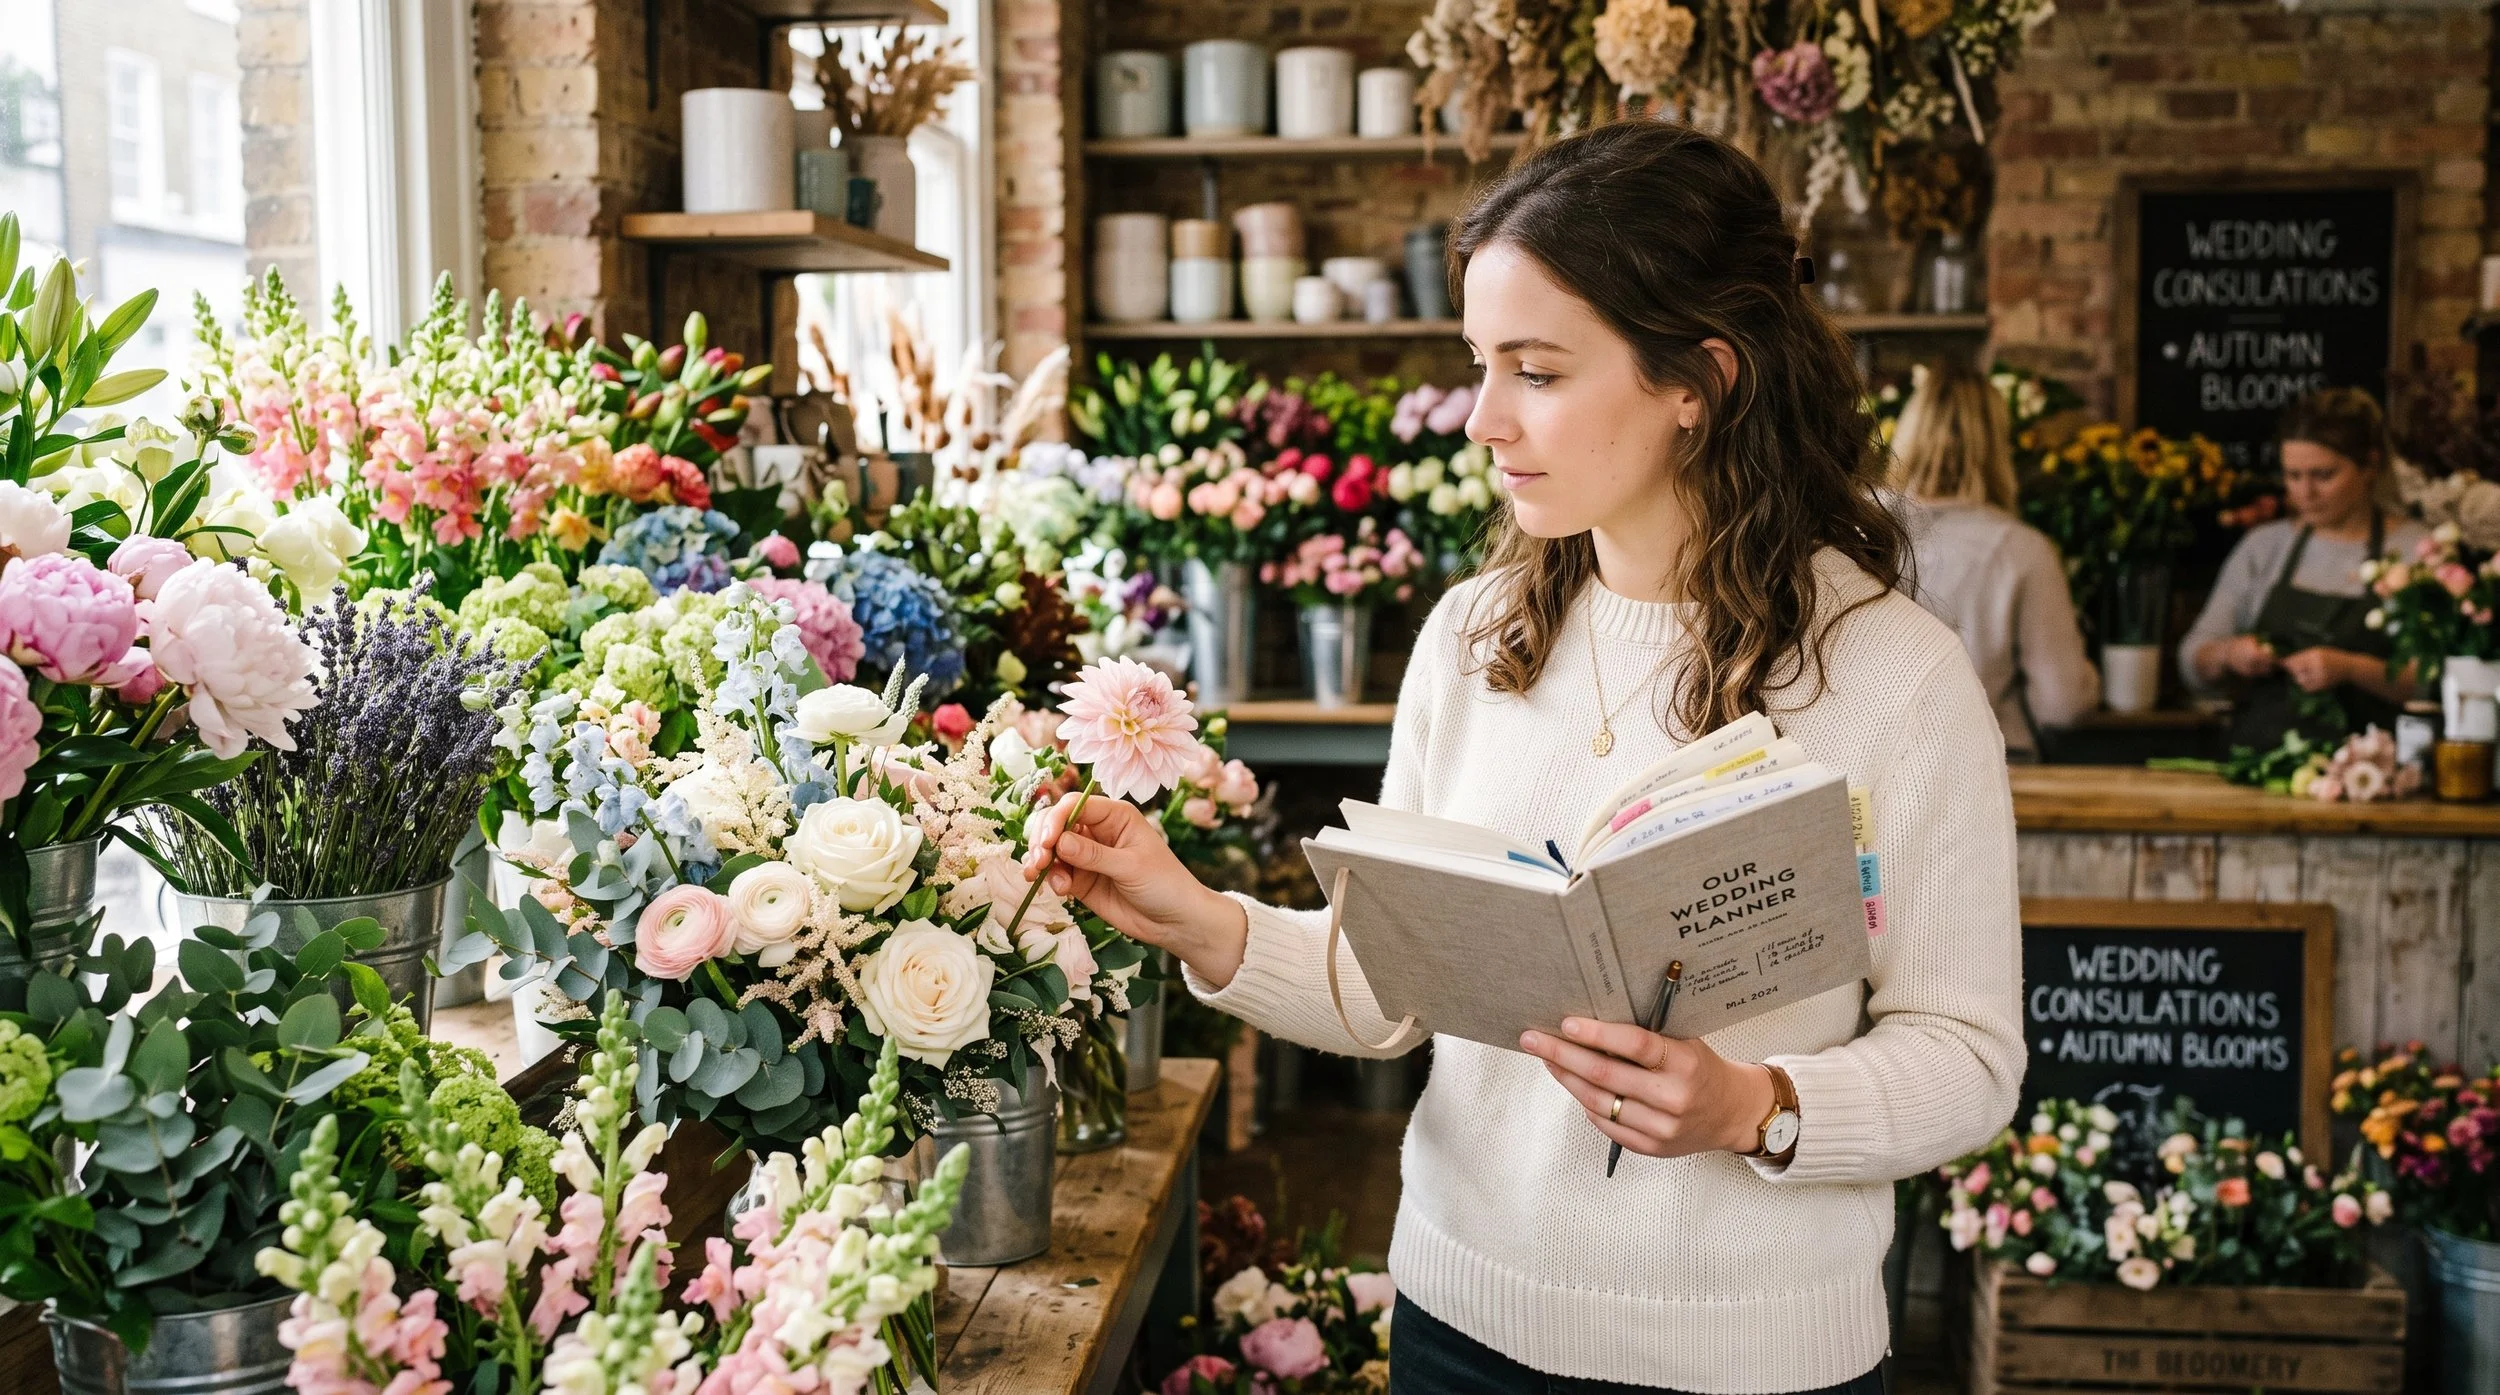
Planning your wedding
Saying yes to the day without saying yes to years of financial stress
There is a particular feeling that hits most couples about two weeks after the engagement, once the excitement settles and the first few quotes land in the inbox. The venue wants a deposit. The photographer is booking out eighteen months ahead. Someone has gently mentioned that catering is priced per head and your guest list has quietly grown to ninety people. Suddenly the happiest decision you have ever made comes with a spreadsheet attached.
If that sounds familiar, you are in very normal company. Weddings in New Zealand have a way of costing more than anyone expects, not because couples are extravagant, but because a wedding is really twenty smaller purchases stacked on top of each other, each of which feels reasonable on its own. The venue, the catering, the photographer, the dress or the suit, the rings, the flowers, the music, the celebrant, the transport, the accommodation and the honeymoon all add up long before anyone has bought a single candle.
The good news is that paying for a wedding is a solvable problem, and it does not have to mean draining your savings, putting the deposit on a credit card or asking your parents for help you would rather not ask for. A wedding loan is simply a personal loan used for the day itself, and used sensibly it lets you lock in the suppliers you actually want while spreading the cost over a set period you have chosen in advance.
What a wedding actually costs, and where the money goes
Before you think about borrowing anything, it helps to see the real shape of the spend. Most of a wedding budget sits in a small number of large line items rather than being spread evenly, which is genuinely useful to know because it tells you where the decisions that matter are.
Venue hire and catering together usually account for the largest share of the total, and the two are often bundled, which makes the venue choice the single biggest financial decision of the whole process. Photography and videography come next for most couples, because you are paying for a skilled professional to spend a full day with you plus the editing that follows. After that come the outfits, the rings, the flowers and styling, the entertainment, the celebrant and the smaller costs that are easy to forget, such as marriage licence fees, hair and makeup trials, guest transport and the wet weather backup you hope you never need.
There are also the costs that sit just outside the day itself. Engagement parties, hen and stag events, accommodation for the night before, and the honeymoon all tend to be planned separately and paid for separately, which is exactly how they end up as a surprise. If you are building a budget, put them on the same page as everything else so you are looking at one honest number rather than four optimistic ones.
Once you have that number, you can work out the part that genuinely matters, which is the gap between what the day will cost and what you will realistically have saved by the time the invoices are due. That gap, not the total, is the amount worth thinking about borrowing. Our guide on creating and sticking to a budget is a good place to start if you want to map that out properly, and our top ten tips to save money on your wedding covers the practical ways to bring the total down before you borrow a cent.
Why couples choose a wedding loan
The most common reason is timing. Wedding suppliers work on deposits, and the best ones book out well in advance, so the money is needed long before the day and often long before you have finished saving. A wedding loan closes that timing gap, letting you secure the venue and the photographer you actually want rather than settling for whoever still has availability six weeks out.
The second reason is certainty. A personal loan from SMB comes with a fixed rate and a fixed term, so you know from the first day exactly what the repayment is and exactly when the loan ends. That is a very different experience from putting wedding costs on a credit card or an interest free deal, where the balance can drift for years and the real cost is much harder to see. If you want the detail on how rates shape what you repay, we have explained it plainly in the impact of interest rates on personal loans.
The third reason is protecting your savings. Plenty of couples could technically empty their savings account to cover the wedding, but doing it leaves them with no buffer at all going into married life. Keeping an emergency fund intact while spreading the wedding cost over a manageable term is often the calmer choice, and starting an emergency fund is worth doing whether you borrow or not.
Borrowing an amount you can comfortably live with
This is the part that decides whether a wedding loan feels like a good decision in two years or a regretted one, so it is worth slowing down for.
Start with the repayment rather than the loan amount. Look honestly at what is left over each pay cycle after rent or mortgage, power, food, insurance, transport and the things you actually spend money on, then decide what you could pay towards a loan every week or fortnight without feeling squeezed. Work backwards from that figure to the amount you should borrow, rather than borrowing a number that sounds about right and hoping the repayments fit around it.
Then think about the year ahead. Married life often brings other plans with it, and a repayment that works comfortably today should still work if you are saving for a house deposit, changing jobs or planning a family. It also pays to remember that a personal loan has an establishment fee and account maintenance fees alongside the interest, all of which are set out on our interest and fees page so you can see the full picture before you decide.
At SMB we assess every application against our credit criteria and our responsible lending obligations, which means we look at whether the repayments are genuinely affordable for you rather than simply whether we can approve the amount. You can read how that works on our responsible lending page, and you can check where you stand before applying using our do I qualify guide. If your circumstances change later, paying the loan down faster is always an option, and we have covered the strategies in how to pay off your personal loan faster.
Small decisions that shrink the amount you need to borrow
The cheapest wedding loan is the smallest one, so the work you do on the budget pays for itself twice. Moving the date to a Friday or a Sunday, or out of the peak summer months, changes venue pricing more than almost anything else you can do. Trimming the guest list is the other big lever, because every guest carries a catering cost, a drinks cost, a stationery cost and a chair.
Beyond that, it is worth separating the things you will remember from the things you will not. Most couples look back and remember the people, the food and the photographs. Very few remember the favours, the elaborate stationery suite or the second round of styling details. Spending generously on the handful of things that matter to you and lightly on everything else is not a compromise, it is simply a clearer set of priorities.
Ready to plan the day rather than the panic
A wedding should be something you look forward to, not something you quietly dread every time an invoice arrives. If borrowing a sensible amount over a term you have chosen is what turns the planning back into the fun part, that is a perfectly good reason to do it.
You can read more about how our wedding loans work, see the full range on our explore our loans page, or apply online at smb.nz when you are ready. It takes about seven minutes, you will get a quick answer, and the final decision about whether the loan is right for you always stays with you. If you would rather talk it through with a person first, our team is easy to reach through our contact page.
Lending criteria, responsible lending checks, fees and terms and conditions apply.
Frequently asked questions
How much can I borrow for a wedding?
The amount depends on your income, your existing commitments and our credit assessment. The more useful question is how much you can comfortably repay, so start there and work backwards.
Is a wedding loan better than a credit card?
A personal loan has a fixed rate, a fixed term and an end date, so you know what you are paying and when it finishes. A credit card balance can drift for years, which usually costs more overall and is harder to plan around.
Can we pay the loan off early?
Yes. Making extra repayments where you can shortens the term and reduces the interest you pay. Our repaying your loan page covers how it works.
When should we apply?
Most couples apply once they have firm quotes and know the size of the gap between their savings and the total cost, which is usually after the venue and the main suppliers have been chosen.
